By David Park, Real Estate & Tax Correspondent
Executive Summary
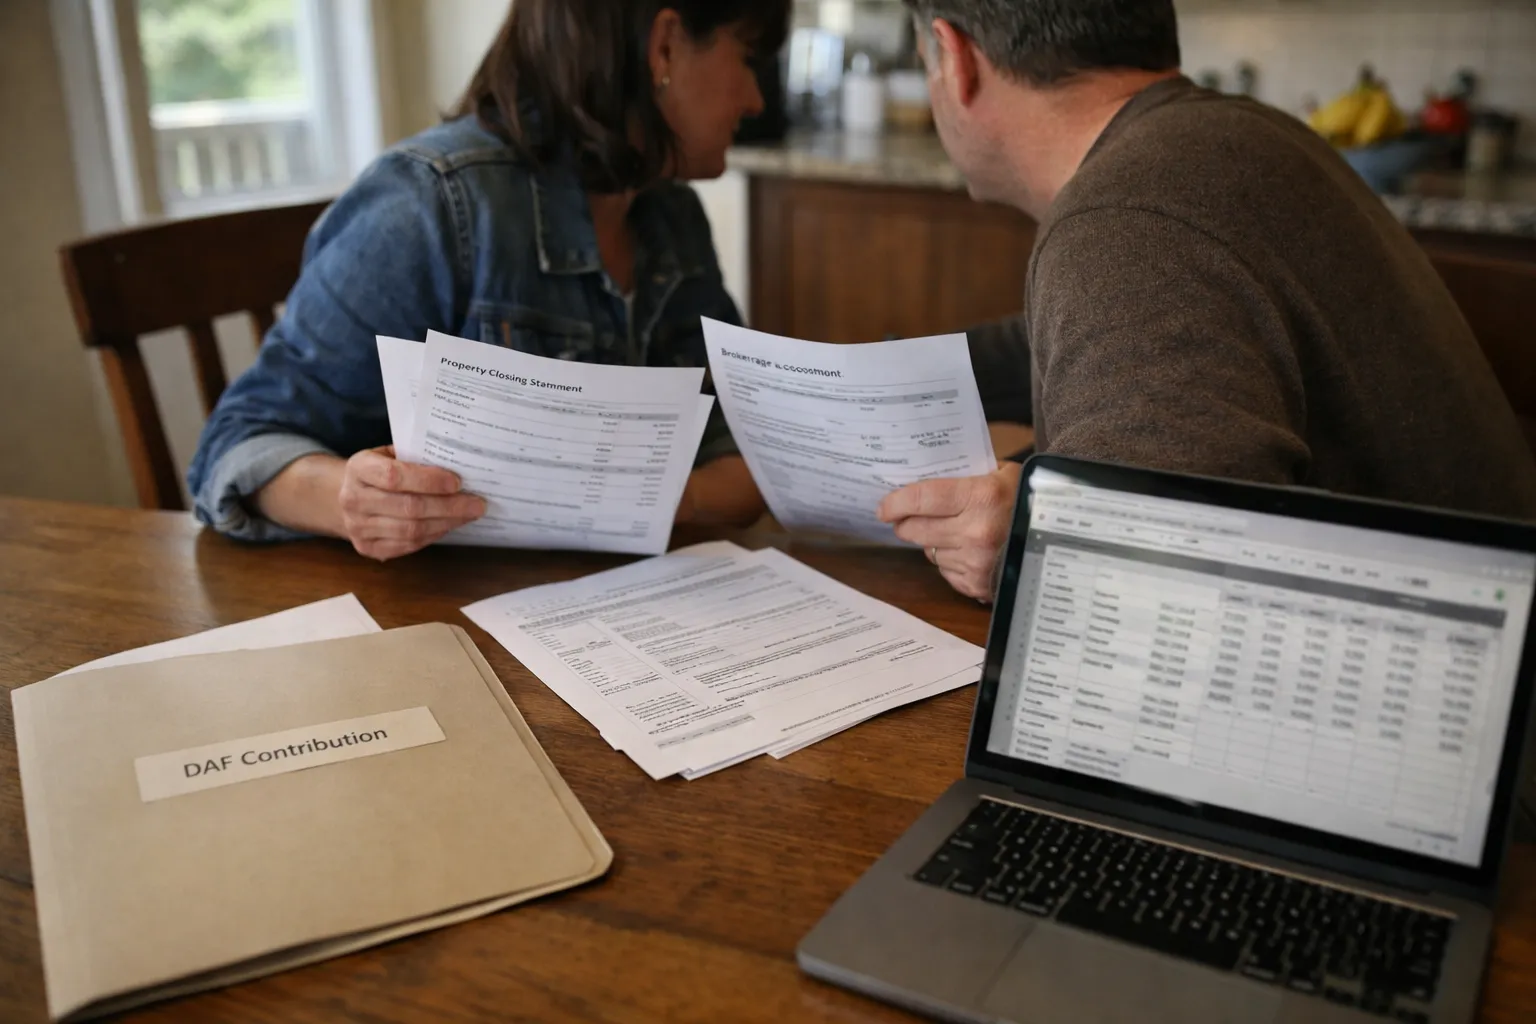
In December 2025 a married couple sold a long-held single-family rental and used an $80,000 donor-advised fund (DAF) gift together with targeted withholding and estimated-tax payments to push a large slice of their long-term capital gains (LTCG) into the federal 0% band. An updated November 2026 review adds operational changes at major DAF sponsors, elevated IRS scrutiny of large noncash gifts, and refined modeling guidance advisers should use now.
Background
Clients: “Maya” (38) and “Chris” (40), married filing jointly, one child; both W-2 employees.
Location: Washington state (no state income tax).
Property: Single-family rental purchased in 2014 for $250,000. CPA records show accumulated depreciation of $85,000 through 2025. The couple sold in December 2025.
Objectives: (1) Close the sale and redeploy proceeds into a diversified portfolio, (2) preserve cash for a primary-home down payment in 3–5 years, (3) avoid unpredictable tax surprises and reduce marginal capital-gains exposure while preserving philanthropic flexibility.
Challenge
The closing created a concentrated, single-year tax spike with three material risks:
- Depreciation recapture: $85,000 of accumulated depreciation taxed as unrecaptured Section 1250 (up to 25%), requiring cash funding irrespective of DAF moves.
- Long-term capital gain exposure: Approximately $250,000 of remaining LTCG whose federal rate (0%, 15% or 20%) depends on the couple’s post-deduction taxable income.
- Cash-tax and compliance risk: Mistimed withholding or underpayment could trigger penalties and a large unexpected tax bill at filing.
Solution
The adviser and CPA executed a two-part, contemporaneous plan:
- Fund a same-year DAF with appreciated securities to create a large, itemized charitable deduction that lowers taxable income and shifts a portion of LTCG into the 0% bracket.
- Coordinate year-end withholding and a Q4 estimated payment to satisfy IRS safe-harbor rules and avoid underpayment penalties.
Rationale: LTCG rates are applied against taxable income. A sizeable itemized charitable deduction in the sale year can move marginal LTCG dollars from the 15% band into 0%. Donating appreciated securities to a DAF avoids immediate recognition of additional gain and preserves economic value for future grants.
Implementation
Step 1 — Decompose the gain
Closing numbers used for planning (rounded):
- Gross sale price: $530,000
- Selling costs: $30,000
- Net proceeds before debt: $500,000
- Original cost basis: $250,000
- Accumulated depreciation: $85,000
- Adjusted basis (simplified): $165,000
- Total gain: $335,000 (of which $85,000 is depreciation recapture)
The CPA separated the $335,000 into $85,000 unrecaptured Section 1250 and roughly $250,000 of LTCG for modeling and cash planning.
Step 2 — Model taxable income and capital-gains buckets
Prior-year combined W-2 wages were about $150,000. Adviser modeling showed an $80,000 DAF gift (funded with long-held index shares) would materially reduce taxable income and shift a significant slice of the ~$250,000 LTCG into the 0% federal band without creating an unusable carryforward under AGI limits.
November 2026 update: LTCG bracket thresholds are indexed annually—don’t rely on a prior-year rule of thumb. Also explicitly model surcharges (NIIT and Medicare IRMAA). Charitable deductions lower taxable income but generally do not reduce MAGI for NIIT/IRMAA purposes; therefore a DAF can move LTCG between brackets yet leave MAGI‑based surcharges intact.
Step 3 — Fund the DAF with appreciated securities
In December 2025 Maya and Chris transferred $80,000 of long-held index-fund shares (held >1 year) to a national DAF sponsor. The sponsor liquidated the shares inside the DAF (no taxable event to donors) and provided a contemporaneous acknowledgement showing date, shares, and cash proceeds. The couple claimed an itemized deduction equal to the FMV of the donated shares, subject to the appreciated‑property AGI limit (typically 30% for public charities) and substantiation rules (Form 8283 when required).
Why appreciated securities: Donating avoids realizing incremental gain; the FMV deduction preserves tax value while creating a multi-year grant inventory.
Step 4 — Coordinate withholding and estimated payments
The couple increased Chris’s withholding in Q4 and made a Q4 estimated payment so they fit within commonly used safe harbors (100% of prior-year tax for many filers, or 110% for higher adjusted gross income). The CPA retained the projection worksheets and DAF acknowledgement to support the year-end positions in case of inquiry.
2026 operational and compliance cautions
- DAF sponsor cutoffs: Since 2024 many large DAF sponsors moved to earlier processing cutoffs (mid-December) for noncash gifts to manage settlement and valuation. Transfer securities well before the sponsor’s stated deadline—ideally 10–14 business days—so the sponsor can sell and acknowledge the gift in the calendar year.
- Documentation expectations: IRS examiners increasingly request donor brokerage transfer confirmations, the DAF sponsor acknowledgment (with date and value), and Form 8283 when required. Retain all communications and brokerage statements showing the in-kind transfer.
- Form 8283 and appraisals: Noncash gifts > $500 require Form 8283; gifts of non‑public property or complex property valued over $5,000 typically require a qualified appraisal and the appraiser’s signature on Form 8283. Publicly traded securities donated through electronic transfer are generally straightforward—but still document FMV and transfer date.
- NIIT, MAGI, and IRMAA: Charitable itemized deductions generally do not reduce MAGI for NIIT/IRMAA determinations. Model the effect of a DAF on both taxable income and MAGI-based surcharges separately.
- Estate and control considerations: Contributions to a DAF are completed gifts and typically removed from your taxable estate. That is an estate-planning benefit—but remember you no longer directly control the charitable asset outside the sponsor’s grant policies.
- State tax divergences: States vary in treatment of charitable deductions and capital gains. In states that tax capital gains as ordinary income or limit itemized deductions, the federal benefit from a DAF may not translate dollar‑for‑dollar.
Results — Modeled outcomes and liquidity planning
Modeled, conservative results the couple used for decision-making (rounded):
- DAF contribution: $80,000 of long-term appreciated securities donated in December 2025.
- Taxable-income effect: The $80,000 deduction materially reduced taxable income for 2025 and pushed a significant portion of the ~$250,000 LTCG into the 0% bracket under the adviser’s model.
- Depreciation recapture: $85,000 remained subject to unrecaptured Section 1250; the couple set aside cash to cover an estimated federal recapture tax of roughly $21,250 (25% top recapture rate used for planning) and tracked it as closing liquidity.
- Underpayment avoidance: Withholding increases plus a Q4 estimated payment kept them within IRS safe-harbors and avoided underpayment penalties.
- Net federal cash-tax outcome: Conservative CPA modeling placed federal cash-tax savings in a range roughly between $12,000 and $30,000 compared with a no‑DAF scenario—variance driven by assumptions about how much LTCG fell into 0% and whether NIIT applied. The DAF also created a charitable grant inventory for future family giving.
Why this matters in November 2026
DAFs remain a practical tactical lever for spike-income events such as property sales. Since 2024 sponsors and examiners have tightened operational controls around in-kind transfers and high-dollar noncash deductions. For advisers that means: (1) start transfer logistics earlier, (2) document every step, and (3) model both taxable-income effects and MAGI-based surcharges separately. For clients building multi‑generational wealth, the strategy converts a one-year tax deduction into a permanent philanthropic capital source while removing value from the taxable estate.
Lessons Learned
1) Treat capital-gains planning as taxable-income planning
Lowering taxable income can change the marginal rate on capital gains. A same-year charitable bunching move is one of the few late-year levers large enough to shift marginal dollars between 0% and 15% LTCG bands—if modeled precisely against current-year thresholds.
2) Separate the buckets and fund the cash obligations
Depreciation recapture requires cash irrespective of charitable moves. Model recapture, LTCG, NIIT, and IRMAA separately so liquidity planning is clear.
3) Start DAF transfer logistics early
Because sponsors shortened noncash cutoffs and settlement windows, initiate transfers 2–3 weeks before the sponsor cutoff and obtain the sponsor acknowledgement with date and value before filing.
4) Document everything
Keep brokerage transfer confirmations, DAF acknowledgements, Form 8283 (if required), appraisal reports (if needed), and the CPA’s projection worksheets to support the positions in an audit.
5) Use liquidity events to reset long-term plans
Sales are opportunities to rebalance portfolios, formalize family philanthropy, and address estate-transfer objectives. A DAF converts a single‑year tax deduction into a multi-year giving vehicle and can be part of a generational wealth plan.
Takeaways
- DAF bunching can be effective in a property-sale year to push LTCG into the 0% band—but model 2026-specific brackets and surcharges precisely.
- Depreciation recapture is generally taxable and must be funded with cash; it isn’t eliminated by a DAF gift.
- Charitable deductions reduce taxable income but generally do not reduce MAGI for NIIT/IRMAA—model both effects.
- Transfer securities to the DAF well ahead of the sponsor’s year-end cutoff, and retain transfer confirmations and sponsor acknowledgements.
- Coordinate federal planning with state advisers—state rules can materially change the net benefit.
FAQ
Will a DAF reduce my exposure to the 3.8% NIIT?
Generally no. The 3.8% Net Investment Income Tax is measured against MAGI and net investment income. Charitable itemized deductions lower taxable income but typically do not reduce MAGI for NIIT calculations, so a DAF may not eliminate NIIT exposure even if it moves LTCG into the 0% bracket.
How far in advance should I transfer securities to a DAF for year‑end credit?
Start the transfer at least 10–14 business days before the sponsor’s stated cutoff; many large sponsors use mid‑December processing cutoffs. Earlier transfers reduce settlement and valuation risk and increase the chance you receive a contemporaneous acknowledgement with the calendar‑year date.
Is a DAF better than a charitable remainder trust (CRT) for large gains?
It depends on goals. A DAF is simple, immediate, and preserves philanthropic flexibility. A CRT can defer recognition of gain, provide an income stream, and offer estate-planning advantages but is more complex and typically irrevocable. Run comparative cash‑flow and tax modeling—CRT can be preferable for very large sales when income and estate objectives matter.
What documentation will an examiner likely request for a large DAF gift?
Examiners commonly request: (1) donor brokerage transfer confirmations showing the in-kind transfer, (2) the DAF sponsor’s written acknowledgement with date and proceeds, (3) Form 8283 when required, and (4) any appraisal supporting value for non-public gifts. Maintain a cohesive file before filing.
When should I start modeling a planned sale?
Start 60–120 days before closing to allow time for alternative structures, appraisals, DAF transfers, and estimated‑payment decisions. Early modeling gives advisers time to compare strategies (DAF, CRT, installment sale) and coordinate state and federal effects.
Disclaimer: This case study is educational and uses simplified, rounded figures. It reflects common federal rules and advisory practices as of November 2026. Individual results depend on full facts, state rules, and year‑specific thresholds. Consult a qualified CPA and estate adviser before implementing similar strategies.