By David Park, Real Estate & Tax Correspondent
Executive Summary
In late 2025 a married couple sold a long-held rental and used an $80,000 donor-advised fund (DAF) gift plus withholding/estimated-tax adjustments to materially reduce taxable income and keep a substantial portion of their long-term capital gains inside the 0% federal band. Depreciation recapture still applied and required cash planning, but the combined approach reduced federal cash taxes due and created a multi-year charitable grant inventory. This June 2026 update adds current compliance cautions (including NIIT and MAGI interactions), operational best practices from recent advisory experience, and clearer modeling guidance advisers can use now.
Background
Clients: “Maya” (38) and “Chris” (40), married filing jointly, one child. Both W-2 employees.
Location: Washington state (no state income tax).
Property: Single-family rental purchased in 2014 for $250,000. CPA records show accumulated depreciation of $85,000 through 2025. The couple sold in December 2025.
Objectives: (1) Close the sale and redeploy proceeds into a diversified portfolio, (2) preserve cash for a primary-home down payment in 3–5 years, (3) avoid unpredictable tax surprises and reduce marginal capital-gains exposure.
Challenge
The closing produced a single-year tax spike with three distinct risks:
- Depreciation recapture: $85,000 of accumulated depreciation that remains taxable as unrecaptured Section 1250 (taxed up to 25%).
- Long-term capital gain exposure: Roughly $250,000 of remaining long-term capital gain that could be taxed at 0%, 15% or 20% depending on post-deduction taxable income.
- Cash-tax and compliance risk: Higher AGI or poorly timed withholding can trigger underpayment penalties and cash surprises at filing.
Solution
The CPA and advisor executed a two-part plan based on long-standing federal mechanics and updated 2026 operational best practices:
- Fund a same-year donor-advised fund with appreciated securities to produce a large itemized charitable deduction that reduces taxable income and shifts marginal LTCG into the 0% bracket.
- Adjust year-end withholding and make targeted estimated tax payments to meet IRS safe harbors and avoid underpayment penalties.
Why it works: Federal LTCG rate tiers are applied against taxable income; a sizeable itemized deduction in the sale year can move marginal capital-gains dollars from 15% into 0%. A DAF lets donors contribute appreciated securities (no taxable event on the donation), claim FMV for the deduction (subject to AGI limits), and preserve the economic value for future grants.
Implementation
Step 1 — Decompose the gain
The couple’s closing numbers (rounded for planning):
- Gross sale price: $530,000
- Selling costs: $30,000
- Net proceeds before debt: $500,000
- Original cost basis: $250,000
- Accumulated depreciation: $85,000
- Adjusted basis (simplified): $165,000
- Total gain: $335,000 (of which $85,000 is depreciation recapture)
The CPA separated the $335,000 into $85,000 unrecaptured Section 1250 and ~$250,000 of remaining long-term capital gain for modeling and cash planning.
Step 2 — Model taxable income and capital-gains buckets
Before the sale the couple expected combined W-2 wages around $150,000 for 2025. The adviser modeled multiple scenarios and determined that an $80,000 DAF gift (funded with long-held index shares) would lower taxable income enough to meaningfully increase the portion of LTCG taxed at 0%—without creating an unusable five‑year carryforward problem under the AGI limits for donated appreciated securities.
Important 2026 reminder: LTCG brackets are indexed annually. Before recommending a DAF, run year-specific bracket thresholds and confirm whether the client itemizes (bunching may be required). Also model Medicare/IRMAA and the 3.8% Net Investment Income Tax (NIIT): charitable deductions do not reduce MAGI, so a DAF can change the capital-gains bracket but will not lower MAGI-based surcharges such as the NIIT or IRMAA.
Step 3 — Fund a DAF with appreciated securities
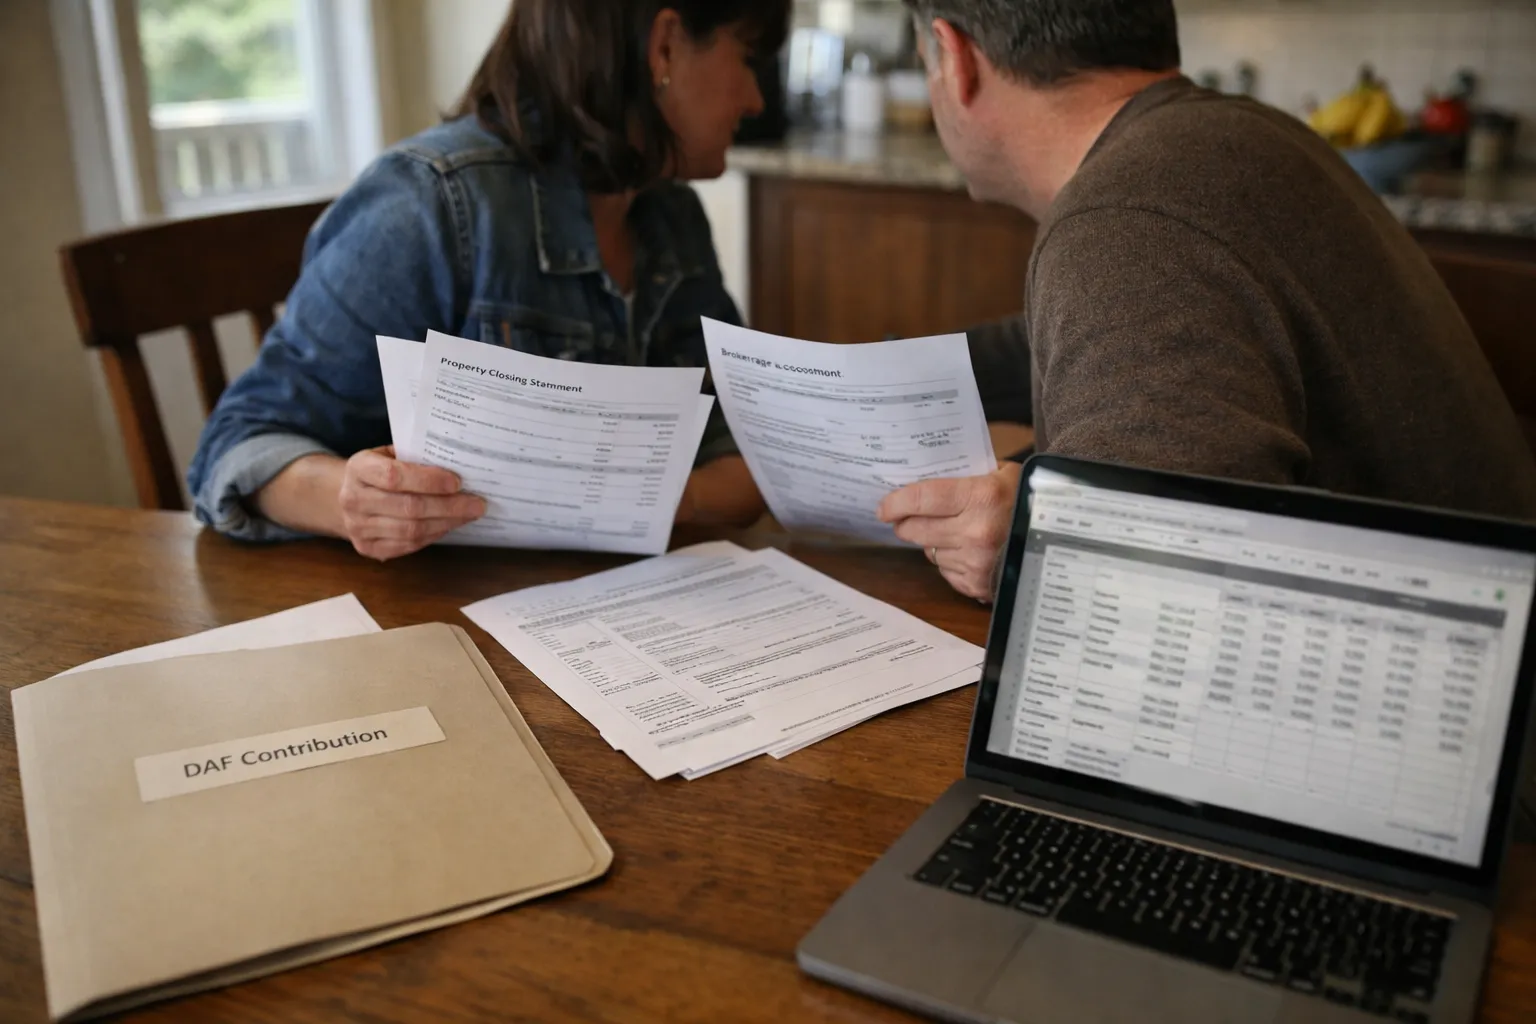
In December 2025 Maya and Chris transferred $80,000 of long-held index fund shares (held >1 year) to a national DAF sponsor. The DAF sold the shares inside the vehicle (no taxable event to the donors) and the couple claimed an itemized charitable deduction equal to the donated shares’ fair market value, subject to AGI limits and substantiation (Form 8283 when required).
Why appreciated securities: Donating the shares avoids recognizing incremental gains, while the FMV deduction is typically available up to the applicable AGI limit (commonly 30% for public charities for appreciated securities). Excess may be carried forward up to five years under IRC rules.
Step 4 — Coordinate withholding and estimated payments
The couple increased Chris’s withholding in Q4 and made a Q4 estimated payment so one of the IRS safe harbors would be met (100% of prior-year tax for many filers, or 110% for higher-income taxpayers). The CPA documented projections and retained worksheets to justify the payments and decisions in the event of later inquiry.
2026 compliance and operational cautions
- Form 8283 and appraisals: Noncash gifts greater than $500 require Form 8283; gifts of property valued over $5,000 typically require a qualified appraisal and the appraiser’s signature on Form 8283. Keep contemporaneous documentation from the DAF sponsor acknowledging the gift.
- NIIT and MAGI: Charitable deductions reduce taxable income but do not reduce AGI or MAGI for NIIT/IRMAA purposes. Large DAF gifts won’t eliminate NIIT exposure that is determined by MAGI.
- DAF surrender of control and estate treatment: Contributions to a DAF are completed gifts and generally removed from your taxable estate—an estate-planning benefit—but they also cede direct grant control compared with a private foundation.
- Documentation and timing: Transfer securities to the DAF sponsor before year-end and obtain the sponsor’s emailed/written acknowledgement with date and value. If using an appraisal, obtain it before filing and attach required forms.
- State tax considerations: In states that tax capital gains as ordinary income or have different deduction rules, the federal DAF benefit may not translate dollar-for-dollar; coordinate with your state adviser.
Results (CPA-modeled, conservative)
These are modeled, rounded results the couple used for decision-making; actual returns will differ by taxpayer.
- DAF contribution: $80,000 of long-term appreciated securities donated in December 2025.
- Taxable-income effect: The $80,000 charitable deduction materially reduced taxable income, shifting a meaningful slice of the ~$250,000 LTCG toward the 0% bracket in the adviser’s model.
- Depreciation recapture: $85,000 remained subject to unrecaptured Section 1250 (up to 25%); the couple set aside cash to cover an estimated federal recapture tax of roughly $21,250 and tracked it as part of closing liquidity planning.
- Estimated tax management: Withholding increases and a Q4 estimated payment placed the couple within commonly used safe harbors, avoiding underpayment penalties.
- Net federal cash-tax outcome: Conservative CPA modeling showed the combined approach reduced federal cash taxes at filing by an estimated range of roughly $12,000–$25,000 relative to a no‑DAF scenario (range reflects different assumptions about how much LTCG moved into the 0% band and whether NIIT applied). The DAF also created a charitable grant inventory for future family giving.
Why this matters in June 2026
DAFs continue to be a practical tactical lever for spike-income events such as property sales. Since 2024 advisers have reported higher IRS scrutiny of large noncash gifts and more careful exam practices for high-dollar deductions. That makes documentation, appropriate appraisals, and conservative modeling essential. Equally important in 2026 is understanding secondary effects: a DAF changes taxable income (which affects LTCG brackets) but does not reduce MAGI (so NIIT and IRMAA can remain unchanged).
Lessons Learned
1) Think of capital-gains planning as taxable-income planning
Lowering taxable income can directly reduce the marginal rate on capital gains. A same‑year DAF gift is one of the few late-year levers large enough to shift marginal dollars between the 0% and 15% bands.
2) Separate gain buckets and model surcharges
Depreciation recapture behaves differently than LTCG. Model recapture, LTCG, NIIT, and any Medicare surcharge separately so cash flows are appropriately funded.
3) Donate appreciated assets when feasible — but watch AGI limits
Donating long-term appreciated securities to a DAF preserves economic value and produces a FMV deduction subject to AGI limits. If the client’s AGI is constrained, consider bunching gifts across tax years or alternatives such as a charitable remainder trust for larger, income-producing sales.
4) Treat tax payments as transaction costs
Adjust withholding and use estimated payments to meet safe harbors; document the decision process and retain calculations used to justify the payments.
5) Use liquidity events to reset long-term plans
Large sales are opportunities to rebalance, formalize family philanthropic governance, and coordinate estate planning. A DAF converts a single-year deduction into a multi-year giving platform while removing assets from the taxable estate.
Takeaways
- DAF bunching can be effective in a property-sale year to push LTCG into the 0% band — but model year-specific thresholds precisely.
- Depreciation recapture is generally taxable and must be funded separately from any DAF benefit.
- Charitable deductions reduce taxable income but do not reduce MAGI for NIIT/IRMAA; plan around those surcharges explicitly.
- Document transfers, appraisals, and DAF acknowledgements; meet the DAF sponsor’s cut-off for year-end processing.
- Review state tax rules and estate implications with advisers before executing DAF moves—state treatment varies materially.
FAQ
Will a DAF reduce my exposure to the 3.8% NIIT?
No. The 3.8% Net Investment Income Tax is calculated using MAGI (modified adjusted gross income). Charitable itemized deductions reduce taxable income but generally do not reduce MAGI. Therefore, a DAF can help shift LTCG between federal capital-gains brackets but typically will not eliminate NIIT exposure.
How do appraisals and Form 8283 affect DAF gifts of securities?
Noncash gifts greater than $500 require Form 8283. Gifts of publicly traded securities are usually valued at fair market value reported by the DAF sponsor, but non‑publicly traded property or complex gifts valued over $5,000 commonly require a qualified appraisal. Obtain the DAF acknowledgement and complete Form 8283 when required—retain these documents with your tax records.
Is a DAF better than a charitable remainder trust (CRT) for a large gain?
It depends. A DAF is simple, immediate, and provides an income‑tax deduction; a CRT can defer recognition of gain, provide an income stream, and offer estate-planning benefits but is administratively complex and irrevocable. For very large, income‑producing gains, a CRT (or sale to a CRT) can be preferable—run the numbers with your CPA and estate adviser.
What if my state taxes capital gains as ordinary income?
State treatment varies. In states that tax capital gains as ordinary income, the federal DAF strategy still affects federal LTCG progression but may produce different state results. Coordinate state modeling with your CPA—some states disallow or limit charitable deductions differently.
When should I start modeling a planned sale?
Start early—ideally 60–90 days before closing. Early modeling lets you identify whether charitable bunching, withholding changes, or alternative structures (e.g., CRT, installment sale) make sense and gives time to obtain appraisals, coordinate DAF transfers, and execute estimated payments to meet safe harbors.
Disclaimer: This case study is educational and uses simplified, rounded figures. It reflects common federal rules and advisory practices as of June 2026. Individual results depend on full facts, state rules, and year-specific thresholds. Consult a qualified CPA and estate adviser before implementing similar strategies.