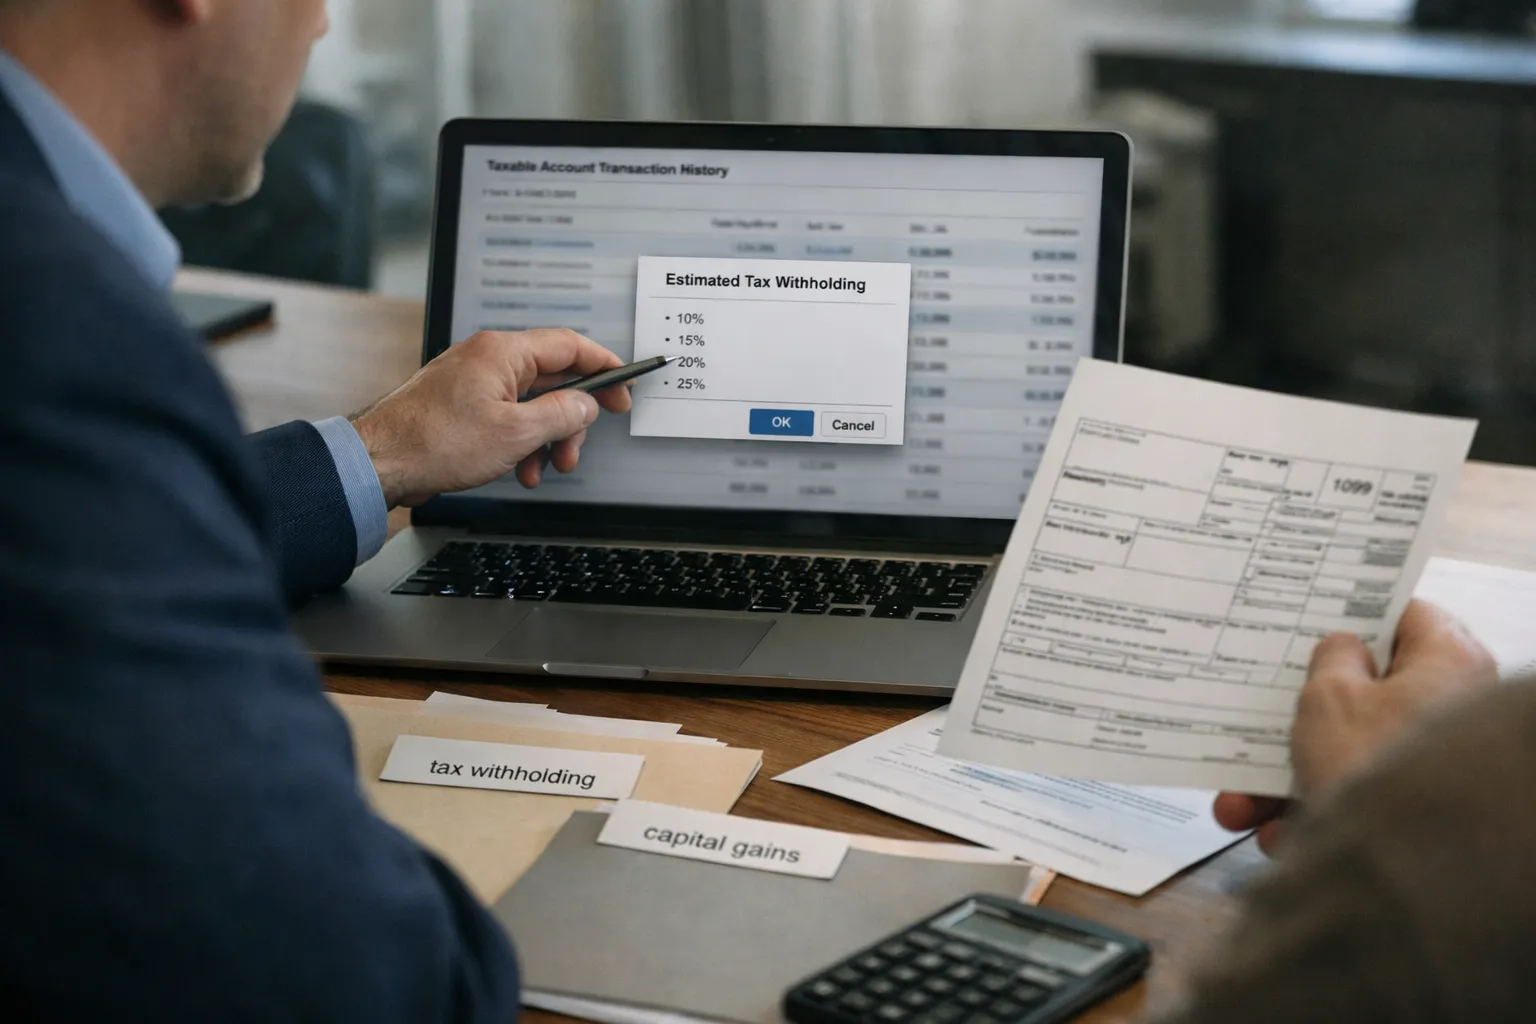
In a move likely to change how advisers manage seasonal and lump‑sum tax exposure, several large custodial brokerages this month launched options that let clients withhold estimated federal (and, in some cases, state) income taxes directly from taxable brokerage and mutual fund accounts. The feature is being pitched as a simple way to manage estimated‑tax obligations tied to realized capital gains, concentrated stock sales, and large distribution events without moving cash into bank accounts or writing separate quarterly checks.
What the new withholding tools do
The new custodial tools allow account holders and their advisers to elect an estimated‑tax withholding percentage (or a dollar amount) that is automatically withdrawn from a specified taxable brokerage account at the time of a sale, dividend payment, or scheduled distribution. Options typically include fixed‑rate presets that match common tax brackets, as well as custom percentage and per‑event amount settings.
For investors who realize gains in irregular bursts—such as when selling an appreciated holding, closing a concentrated position, or receiving a large capital gain distribution from a mutual fund—this automates a step that previously required moving proceeds to a bank and then making an estimated tax payment to the IRS or state.
Why planners care
- Estimated taxes: The new capability reduces missed or underpaid estimated‑tax payments following lump‑sum gains, lowering exposure to underpayment penalties.
- Capital gains management: Withholding can be calibrated to anticipated capital gains tax at different rates (long‑term vs. short‑term) and can be synchronized with harvest trades or disposition plans.
- Tax‑efficiency and cash flow: Clients avoid cash‑drag or extra transfers during retirement or transition years by keeping proceeds in the brokerage account until a withholding event triggers.
- Filing status and credits: For households with changing filing status or eligibility for credits that are sensitive to AGI, withholding from the source gives advisers firmer control over year‑end tax outcomes.
Practical limits and planning considerations
Advisers should note several limitations that affect practical use:
- Withholding is an estimate. It does not change the character of income: withheld amounts are prepayments, not a substitute for final tax calculations when filing. Clients still reconcile deductions, credits, and final tax liability on Form 1040.
- State withholding varies. Not all custodians offer automatic state withholding from taxable accounts, and not all states accept withholding for certain income types—so planners must confirm state rules before relying on the tool.
- Short‑term vs long‑term treatment. Because short‑term capital gains can be taxed at ordinary rates, clients with mixed holdings should consider how a single withholding percentage may under‑ or over‑match ultimate tax liability across different tax brackets.
- Timing and estimated‑tax safe harbors. Automatic withholding tied to disposition events may not satisfy quarterly estimated‑tax safe‑harbor timing for taxpayers dependent on even income flows; advisers should compare withholding schedules against safe‑harbor timing to avoid penalties.
How advisers are using the feature
Advisers interviewed by industry publications are using withholding from taxable accounts in three common scenarios:
- Concentrated‑position sales: Locking in a portion of sale proceeds to cover expected federal tax on realized capital gains, reducing the chance a client will spend proceeds needed for tax payments.
- Mutual‑fund capital gain distributions: Electing withholding at the fund distribution date to capture tax that can otherwise surprise investors in high‑distribution years.
- Periodically variable income: Gig‑economy clients, seasonal sellers, and those with bonus‑heavy compensation schedules are electing per‑event withholding to smooth their estimated‑tax burden.
Example
A married couple filing jointly in the 24% marginal tax bracket who sells an appreciated holding and expects $150,000 of long‑term capital gain might elect a 15% withholding rate for that event to start covering federal capital gains tax. Withholding would prepay $22,500 at the time of sale; the couple would still reconcile final tax when filing, accounting for deductions and any credits that could lower final liability.
Regulatory and recordkeeping implications
Custodians provide clients with Form 1099 and internal transaction records showing amounts withheld for taxes. Advisers should ensure these withholdings are properly reflected when estimating quarterly payments or when calculating whether a client will meet safe‑harbor thresholds based on prior‑year liability or 90% of current year tax.
Because withholding from a taxable account is a prepayment mechanism rather than a tax election, it does not change the legal filing status or eligibility for refundable credits. For clients whose filing status may change (married filing separately vs. jointly), planners should model how withholding levels interact with potential differences in standard deduction and bracket thresholds.
What to watch next
The custodial rollouts are likely a first step. Expect expanded functionality—such as withholding that differentiates long‑term and short‑term gain estimates, better state withholding coverage, and API access for advisors' planning tools—over the next 12–18 months as demand grows. Tax‑planning professionals should update playbooks to include custodial withholding as a complementary tool alongside traditional estimated‑tax payments and safe‑harbor strategies.
For now, withholding from taxable accounts offers a practical, operationally simple way for many clients to cover estimated taxes arising from capital gains and other uneven income—while leaving year‑end tax planning, deductions and credits, and final filing decisions squarely within the adviser’s strategic remit.