Who: U.S. taxpayers and tax-planning enthusiasts. What: an updated, actionable list of nine commonly missed federal tax credits and how to secure them. When: July 2026 (mid-tax year, prime time for corrective moves). Where: on your 2026 federal return and in-year filings such as Marketplace updates. Why: credits cut your tax bill dollar-for-dollar; many filers lose them through timing, paperwork gaps, or false assumptions.
Context: why a July 2026 update matters
Credits remain the most efficient lever in tax planning: a $1,000 credit trims your bill by $1,000; a $1,000 deduction reduces taxable income, not tax. Midway through 2026 the practical landscape looks more administrative than legislative—most major tax law changes affecting credits came with the Inflation Reduction Act (2022) and earlier changes. What’s changed this year is enforcement and reporting: providers, dealers and exchanges are generating more electronic feeds and the IRS’ matching systems are catching mismatches earlier in the cycle.
That matters because we don’t lose credits to arcane law so much as we lose them to paperwork and timing. The playbook below keeps the nine high-value, commonly missed credits from the original June 2026 guide but adds the specific July 2026 realities—new documentation friction points, practical examples and up-to-the-minute recommended moves.
Updated 2026 Playbook: nine “free-money” credits to chase before year-end
1) Saver’s Credit (Form 8880)
Why it’s missed: filers misjudge MAGI after pre-tax moves. New 2026 reality: many employers increased automatic 401(k) deferrals in 2025–26; that can push some taxpayers into Saver’s Credit eligibility without thinking. Immediate play: check year-to-date pre-tax contributions and bump deferrals if you’re on a phaseout threshold. Confirm your employer’s payroll cutoff for year-end changes.
2) Child and Dependent Care Credit (Form 2441)
Why it’s missed: missing provider TINs. July 2026 note: gig-economy childcare platforms and short-term camp providers increasingly provide electronic receipts but not TINs—don’t accept a platform name alone. Immediate play: insist on the provider’s SSN/EIN or a signed statement with name, address and TIN and keep proof of electronic payment.
3) American Opportunity Tax Credit (Form 8863)
Why it’s missed: academic-year timing. 2026 update: universities are increasingly splitting tuition billing across terms and issuing revised 1098‑T entries in summer; that can move a qualifying expense into the wrong tax year. Immediate play: work with the bursar’s office to map which term was paid and request a corrected 1098‑T if necessary.
4) Lifetime Learning Credit (Form 8863)
Why it’s missed: employer tuition reimbursement confusion. New trend: employers that rolled out expanded tuition benefits in 2025 are retroactively reporting assistance in 2026 payroll runs, which can change eligibility. Immediate play: separate reimbursed and out-of-pocket expenses and retain course descriptions to prove eligibility.
5) Residential Clean Energy Credit (Form 5695)
Why it’s missed: placed-in-service disputes. 2026 reality: installers and utilities are tightening interconnection certifications—some local authorities now require final inspection before a system is “placed in service.” Immediate play: get dated inspection receipts, interconnection confirmation from your utility, and the installer’s equipment spec sheet in writing.
6) EV Credits (Form 8936 and dealer disclosures)
Why it’s missed: documentation at purchase. Developments in 2026: manufacturers and dealers are more frequently issuing VIN- and model-specific eligibility letters because of battery sourcing rules. Immediate play: before signing, get a signed dealer certification that includes VIN, model year, and any manufacturer sourcing statement. Keep the purchase contract and request confirmation the dealer will report required information to the IRS.
7) Premium Tax Credit (Form 8962)
Why it’s missed: projected vs. actual income mismatch. 2026 note: midyear job changes and side‑gig income remain the top cause of large reconciliations. Immediate play: update HealthCare.gov or your state exchange promptly when income changes and—if you expect substantial nonwage income—make estimated tax payments or increase withholding to reduce reconciliation shocks.
8) Earned Income Tax Credit (EITC)
Why it’s missed: eligibility complexity. July 2026 reality: EITC filters and automated notices arrive earlier; however, filers with multiple employers or part-year work still run into reporting inconsistencies. Immediate play: reconcile W-2s and 1099s as they arrive; if you had job changes, run an eligibility screen in tax software or with a preparer before filing.
9) Credits that die by one missing form
Why it’s missed: mismatches and missing slips. Practical move: build a “credit folder” (digital and backed-up) and file incoming 1098-T, 1095-A, 1099s, contractor 1099-NEC/1099-MISC, and any provider TINs as they arrive. In July 2026, this is not optional—electronic matching is faster and the first round of IRS notices hits earlier in the season.
Concrete steps you can take this week (July 2026)
- Estimate 2026 MAGI and identify credits with phaseouts near your number. Use reputable tax software or your preparer’s estimator.
- Adjust payroll deferrals now—401(k), HSA—if you’re on the Saver’s Credit cusp; confirm payroll cutoff dates and employee portals.
- Request provider TINs and signed statements at the time of payment for childcare, household help and installers.
- Contact schools and employers immediately if 1098‑T or tuition assistance postings look incorrect; ask for corrected forms dated and emailed.
- Get dealer/manufacturer EV letters and utility interconnection confirmations in writing before year-end; don’t rely on verbal assurance.
- If Marketplace income changes, update it within three business days and document the update confirmation.
- Run an EITC eligibility check if you experienced part‑year work, seasonal income or new gig earnings.
Impact: who benefits—and who loses—this year
Organized filers and proactive preparers win. Households with stable year-round wages have an easier ride; those with midyear volatility—new jobs, side gigs, seasonal work—face reconciliation risk and need to be proactive. Small-business owners and gig workers must front-load documentation because 1099s and business receipts often arrive late and cause year-end surprises.
Reactions from the field
Tax preparers and practice groups I spoke with in June–July 2026 (national enrolled agents and mid‑size preparer firms) stressed the same point: the law hasn’t gotten friendlier to sloppiness. The competitive edge is organizational—track the single credit you’re likeliest to qualify for and file the paperwork now.
What’s next — what to watch through year-end
Watch Treasury and IRS guidance for any clarifications on EV battery sourcing and energy credit place-in-service rules; those clarifications typically surface in the fall. Also watch payer and platform reporting updates—marketplaces and large payroll providers will push more electronic data feeds in late 2026, which can either simplify reconciliation or trip filers who lag on documentation. Plan year-end moves (retirement deferrals, timing capital gains) with your preparer in October or November rather than in December’s rush.
One last play
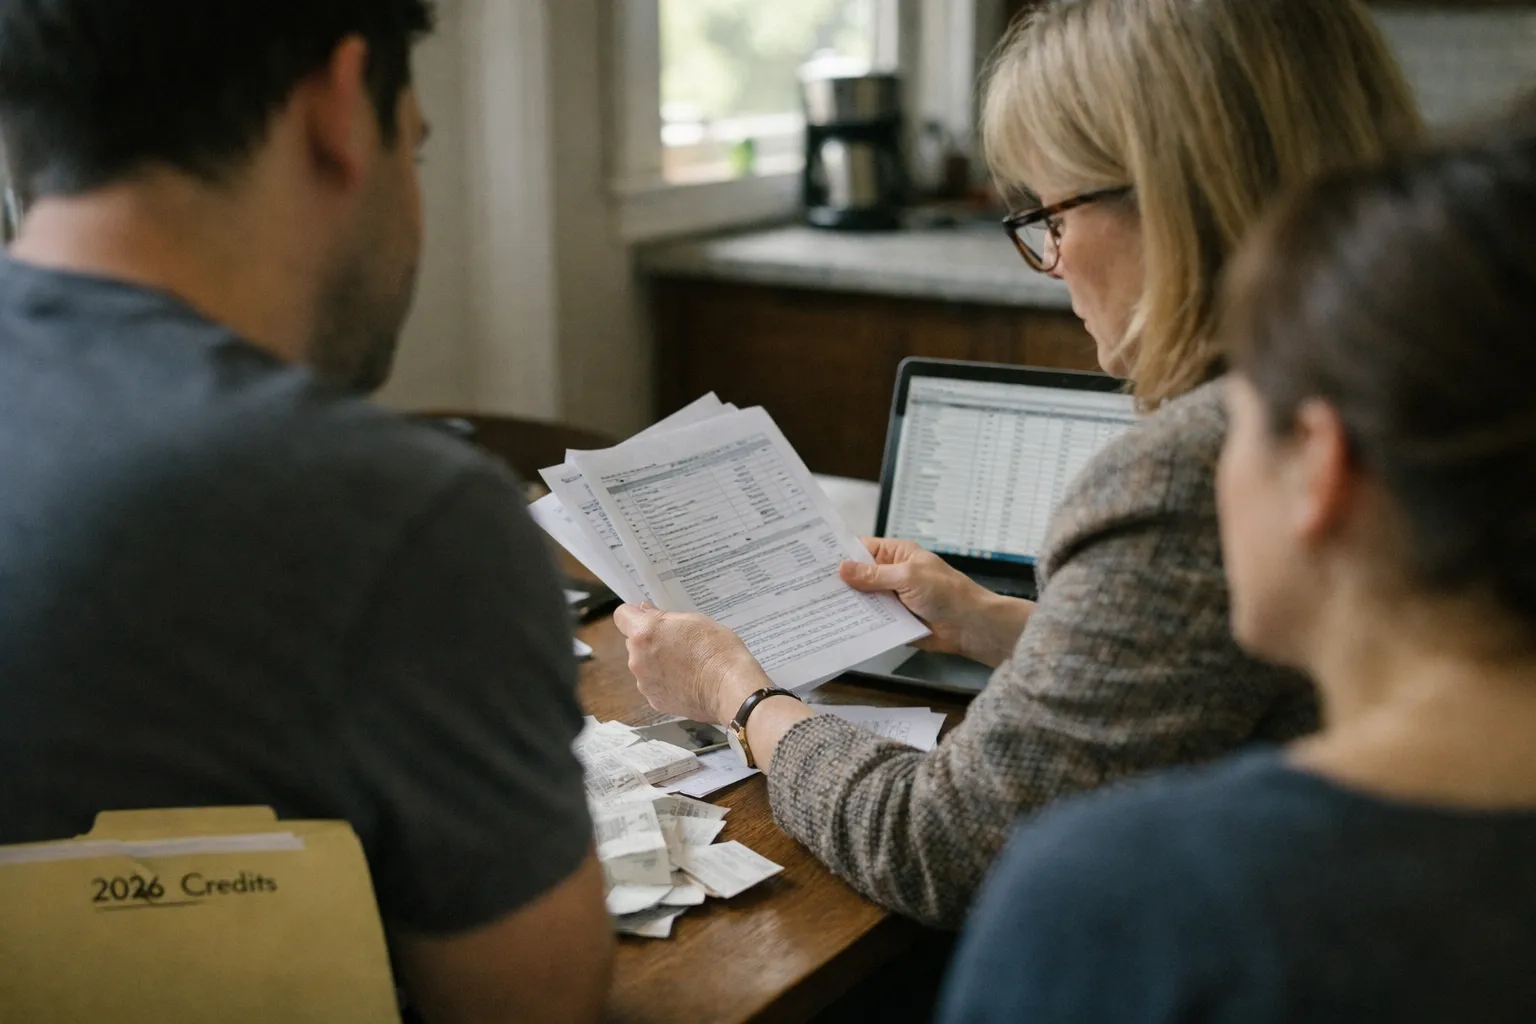
Do one thing today: pick the single credit you’re likeliest to qualify for and create a labeled digital folder (“2026 Credits — Saver’s,” for example). Drop in the form numbers—8880, 2441, 8863, 5695, 8936, 8962—and the specific receipts as they arrive. Organization is the competitive advantage the tax code actually rewards.
FAQ — Quick answers
How do I know whether to increase 401(k) deferrals to qualify for the Saver’s Credit?
Estimate your 2026 MAGI using year-to-date wages, expected bonuses and side income. If that estimate sits near a Saver’s Credit phaseout, increasing pre-tax 401(k) or HSA contributions before your employer’s payroll cutoff can reduce MAGI and flip eligibility. Run the numbers in tax software or with your preparer to confirm.
My dealer says my new EV is “eligible.” What documentation should I insist on?
Get a written dealer statement that includes the VIN, model year, purchase price, and any manufacturer-origin or battery-sourcing certification the dealer can provide. Keep the signed sales contract and request confirmation that the dealer will report required sales data to the IRS.
When should I update Marketplace income to avoid a big reconciliation?
Update your projected annual income with HealthCare.gov or your state exchange as soon as a change is likely—job changes, significant side income, or an expected raise. Also consider increasing withholding or making estimated tax payments if you expect material nonwage income.
What’s the quickest paperwork mistake that kills energy and childcare credits?
Missing or incorrect provider TINs and no dated proof of placement-in-service (for energy) or payment (for childcare). Fix this by verifying TINs and collecting dated inspection/interconnection or payment confirmations when the transaction occurs.